Trump account vs 529 — the smart order for your next dollar
Trump account vs 529 is the wrong question. The $1,000 seed is free money; the 529 is the only account where school withdrawals come out tax-free.
Independent money education for US readers. Not financial advice.

Education, not advice. Written for US readers.
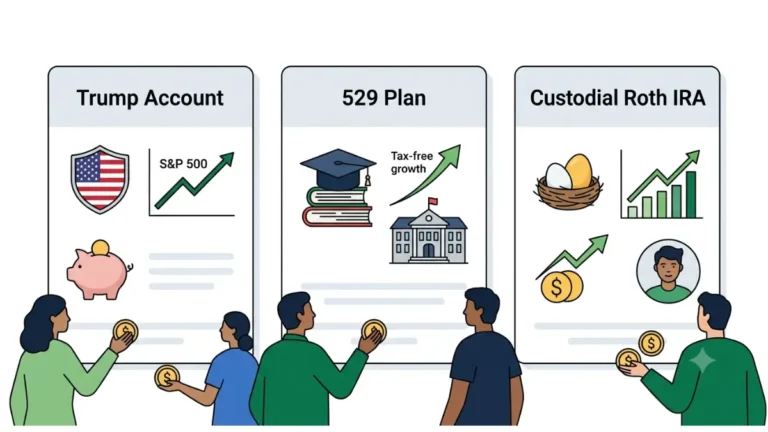
Trump account vs 529 is the wrong question. The $1,000 seed is free money; the 529 is the only account where school withdrawals come out tax-free.
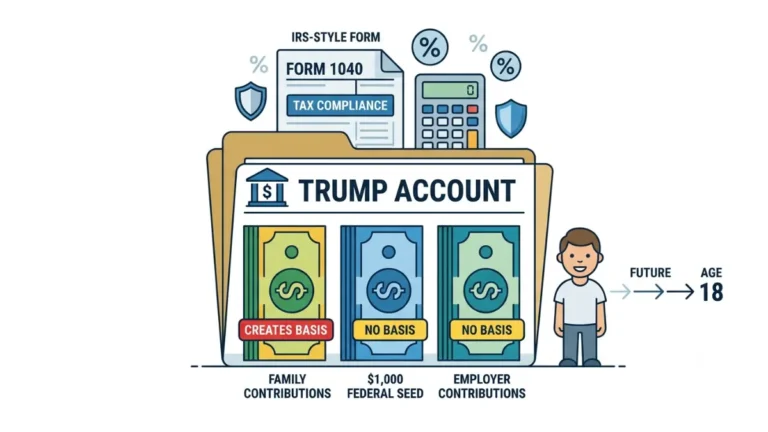
Trump account basis comes from one source only: contributions by individuals. The $1,000 federal seed and employer dollars are taxed in full.
Trump accounts for kids are open, and the $1,000 is real — but the free money creates no basis, so every dollar of it is taxed as ordinary income later.
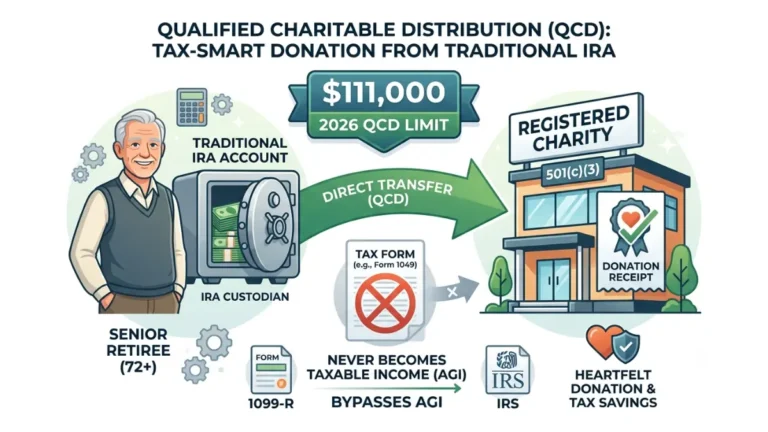
Qualified charitable distributions let IRA owners 70½ and older exclude up to $111,000 in 2026 — and the AGI drop matters more than the tax saved.
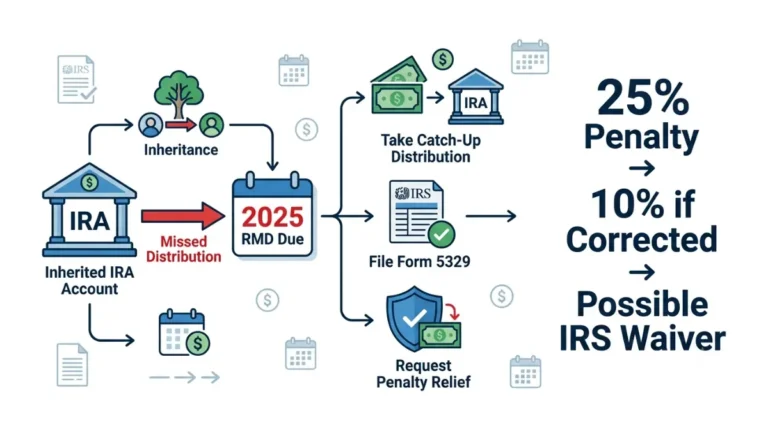
Missed inherited IRA RMD? Most coverage collapses two very different failures into one — and only one of them carries an automatic IRS waiver.
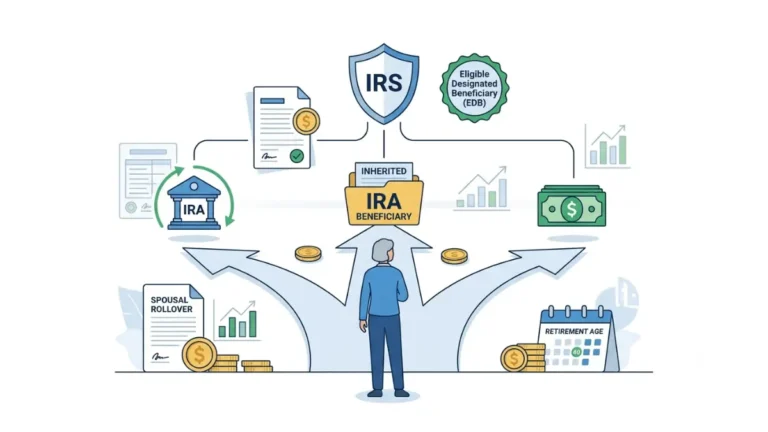
Inherited IRA spouse rules work differently: a surviving spouse skips the 10-year rule most heirs face — and can avoid the early-withdrawal penalty.
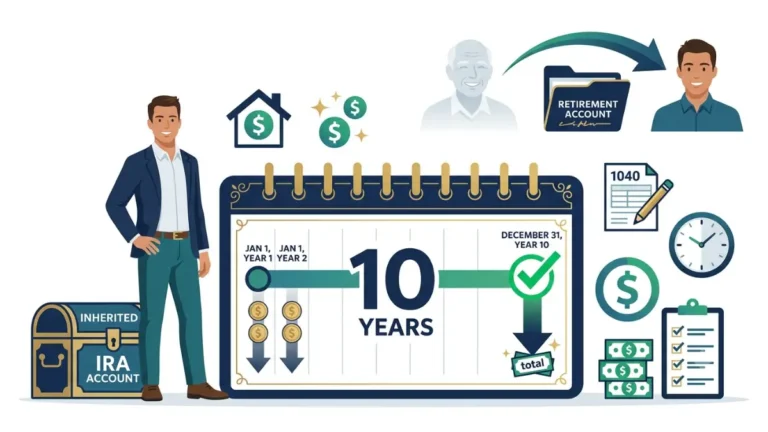
Inherited an IRA? The 10-year rule sets a December 31 deadline in year 10 — and whether you owe a yearly withdrawal hinges on one fact about the owner.
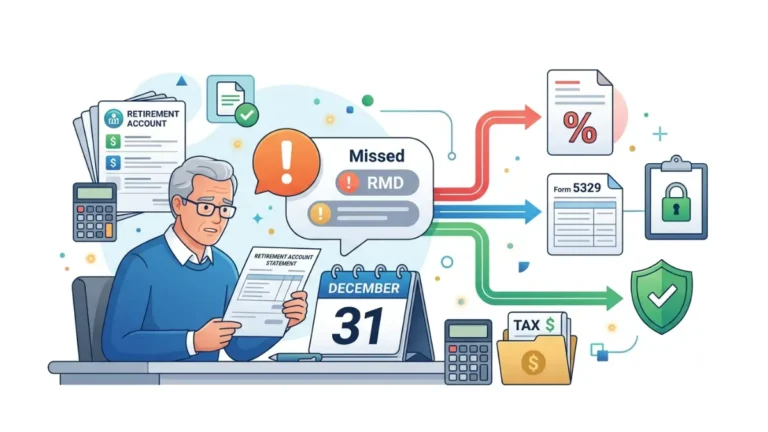
Missed an RMD? The 25% penalty drops to 10%—sometimes to nothing—if you take the distribution and file Form 5329 before your correction window closes.
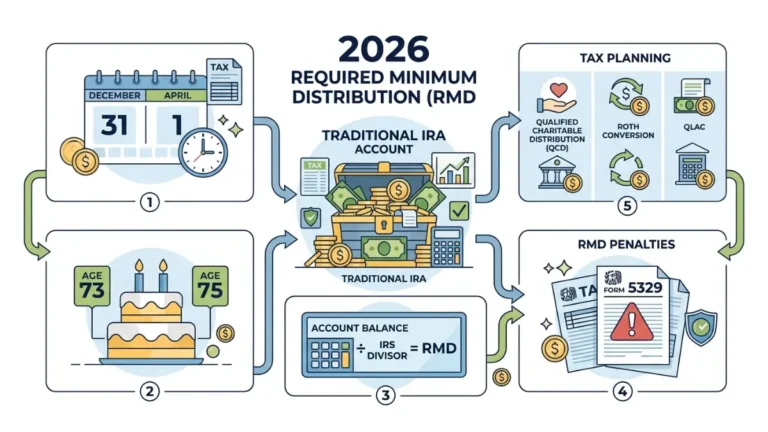
The 2026 RMD rules split retirees by birth year—73 or 75—and add a 25% penalty for a missed withdrawal. Here’s how to find your number and deadline.
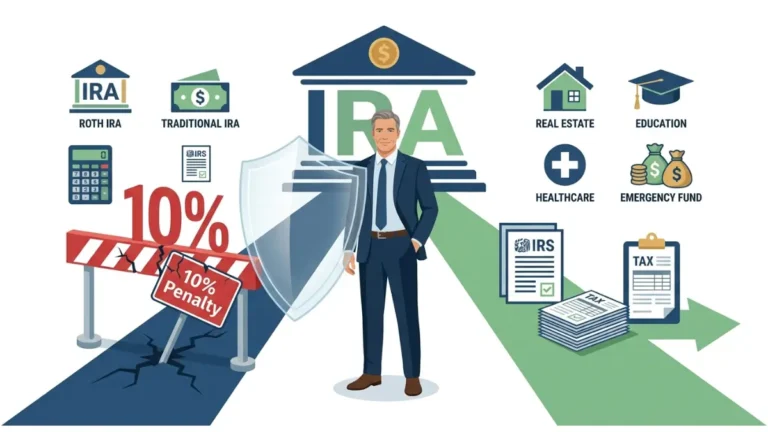
A penalty-free IRA withdrawal is possible through 14 IRS exceptions—first home, medical bills, a $1,000 emergency. But penalty-free isn’t tax-free—see which one fits.