How the 2026 Roth IRA Income Limits Actually Work
Roth IRA income limits rose for 2026: singles phase out from $153,000, couples $242,000. See the exact amount the IRS worksheet allows at your income.
Independent money education for US readers. Not financial advice.

Education, not advice. Written for US readers.
Roth IRA income limits rose for 2026: singles phase out from $153,000, couples $242,000. See the exact amount the IRS worksheet allows at your income.
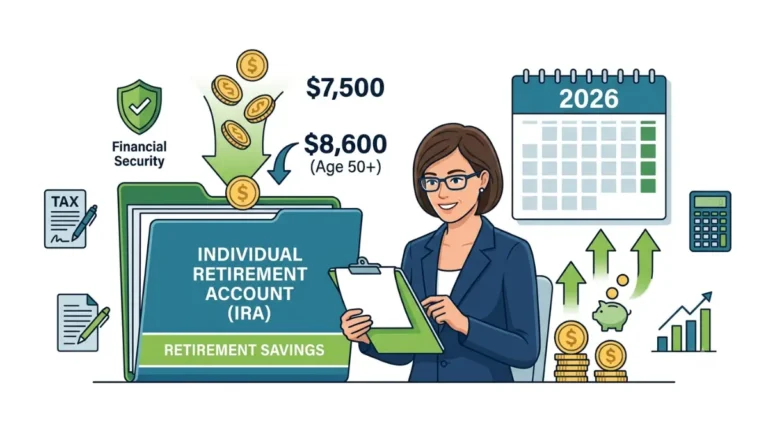
IRA contribution limits rose for 2026: $7,500, or $8,600 at 50+. Your income decides if you can use a Roth or deduct a Traditional. See where you stand.
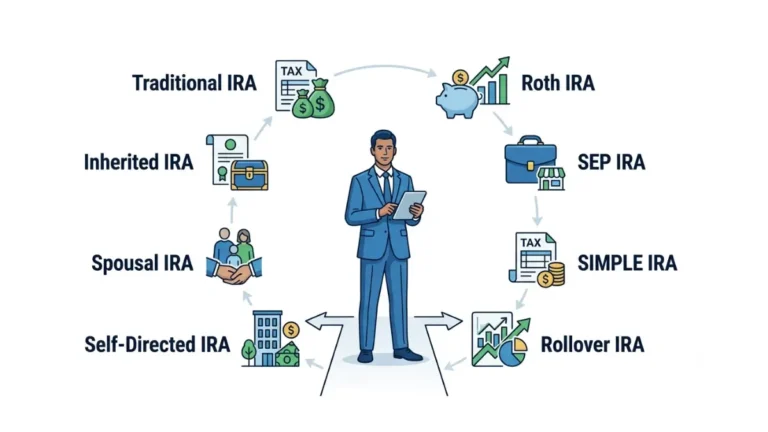
IRA accounts face four income tests, not one. And 2026 is the last year the Saver’s Credit applies to them. See which of the 5 types your income allows.
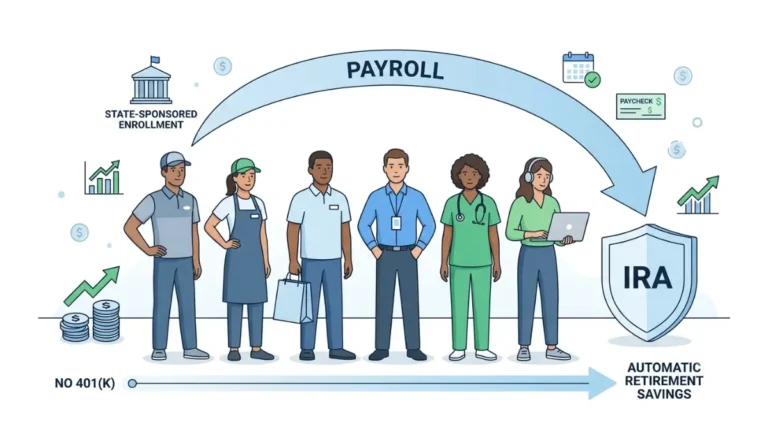
No 401(k)? A state auto-IRA can auto-start your retirement savings — but its Roth setup may block the 2027 Saver’s Match worth up to $1,000.
The 2027 Saver’s Match turns $2,000 in contributions into $3,000 — but one Roth account rule can cost you the entire $1,000.
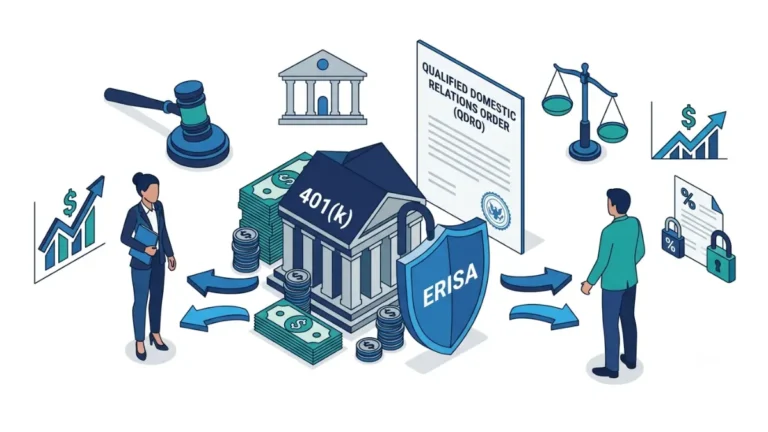
A 401(k) divorce split needs a QDRO—and the receiving spouse avoids the 10% early-withdrawal penalty, even under age 59½.
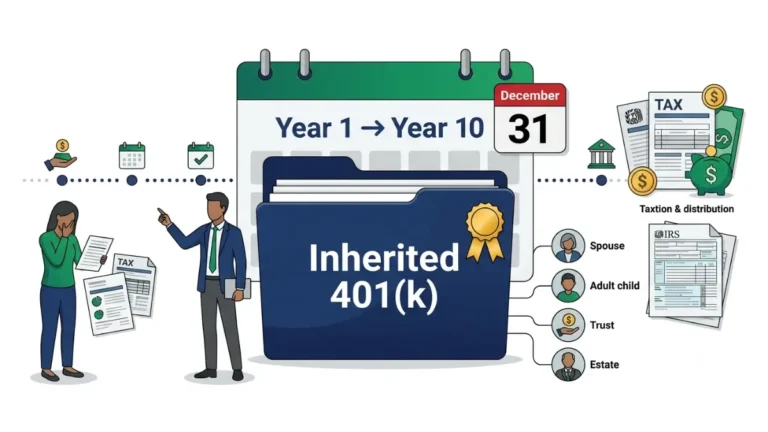
Inherited 401(k) rules trip up most heirs on one point: whether you owe a withdrawal every year, or can wait until year 10. The answer hinges on one date.
Catching up on retirement after 50 isn’t hopeless—2026 hands you an extra $8,000 in 401(k) catch-up room, and a new Roth rule hits earners over $150,000.
A 401(k) in your 20s has one edge nothing later can match: time. Here’s how the 2026 limit, the employer match, and compounding actually build a balance.
Most 401(k) fees are invisible—skimmed from your returns before you ever see them. The average is just 0.26%; here’s how to find yours and pay less.