Medigap birthday rule states and how to find your right window
Medigap birthday rule states differ more than published lists show: California’s window opens on your birthday, Oregon’s 30 days before it.
In This Article
If your Medigap premium climbed again this year, you may not be stuck with it. Fifteen states let people who already hold a Medicare Supplement policy switch once a year without answering a single health question, and New Mexico joins them in 2027.
Where you go next depends on your situation. Already hold a policy in one of those states? The table in the next section gives your exact window. Not sure the rule covers the switch you want? Three restrictions decide that, and they are laid out below. Your state isn’t listed? Skip ahead — other routes exist, and one applies everywhere.
ℹ️ Financial Disclaimer: This article is educational and is not personalized insurance, tax, lending, investment, or debt-relief advice. Medicare Supplement rules are set by state insurance law and change during legislative sessions. Confirm your own eligibility with your state department of insurance or a licensed agent before applying, and consult a CPA or qualified attorney for questions about how coverage decisions affect your taxes or estate.
What the Medigap birthday rule actually does
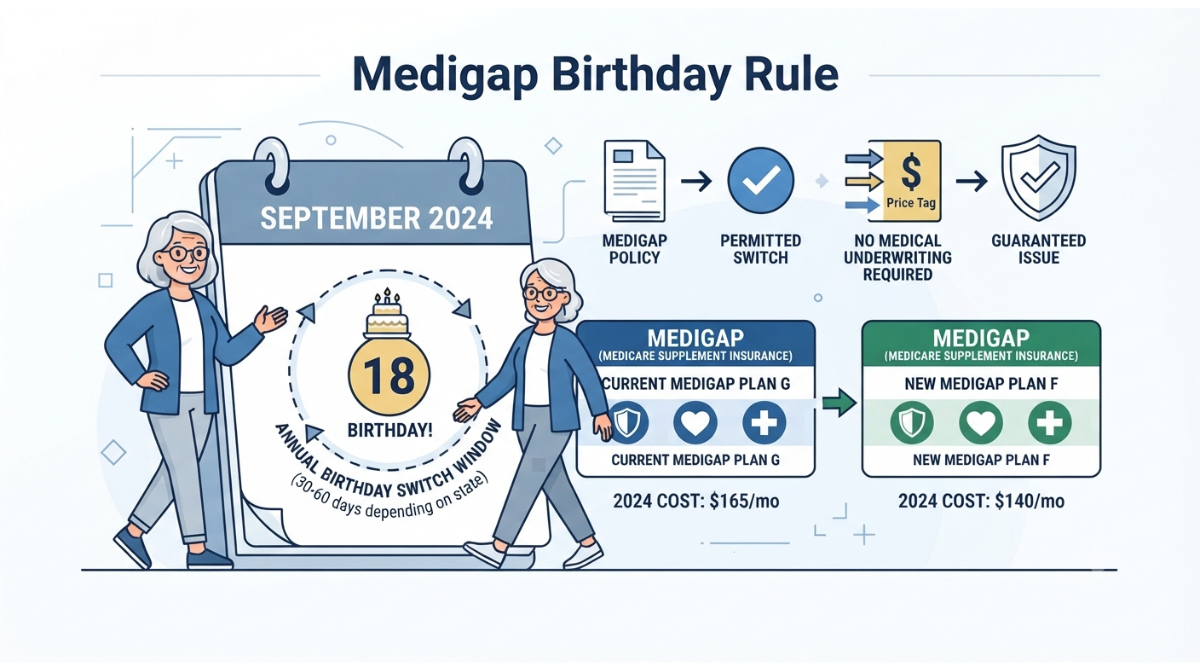
The birthday rule is a state-created annual window in which someone who already has a Medigap policy can move to another one without medical underwriting — no health questions, no denial for pre-existing conditions.
Your one federal window, and why it closed
Federal law gives most people a single protected shot at Medigap. The Medigap open enrollment period runs six months and begins once you are at least 65 and enrolled in Medicare Part B. Both conditions must be met for the clock to start.
After it closes, insurers in most states may underwrite your application. The birthday rule is a state exception carved into that federal default — not a Medicare benefit.
Why this is not the October-to-December enrollment period
The annual period running October 15 to December 7 covers Medicare Advantage and Part D, not Medigap. Confusing the two is the most common reason people miss their actual window. The dates that govern each Medicare enrollment period are worth checking separately.
🔍 How It Works: Medigap letters are standardized, so a Plan G bought from one insurer covers exactly what a Plan G from another covers. Only the premium differs. That is what makes a guaranteed-issue switch worth doing — you change the price, not the coverage.
Which states have a Medigap birthday rule
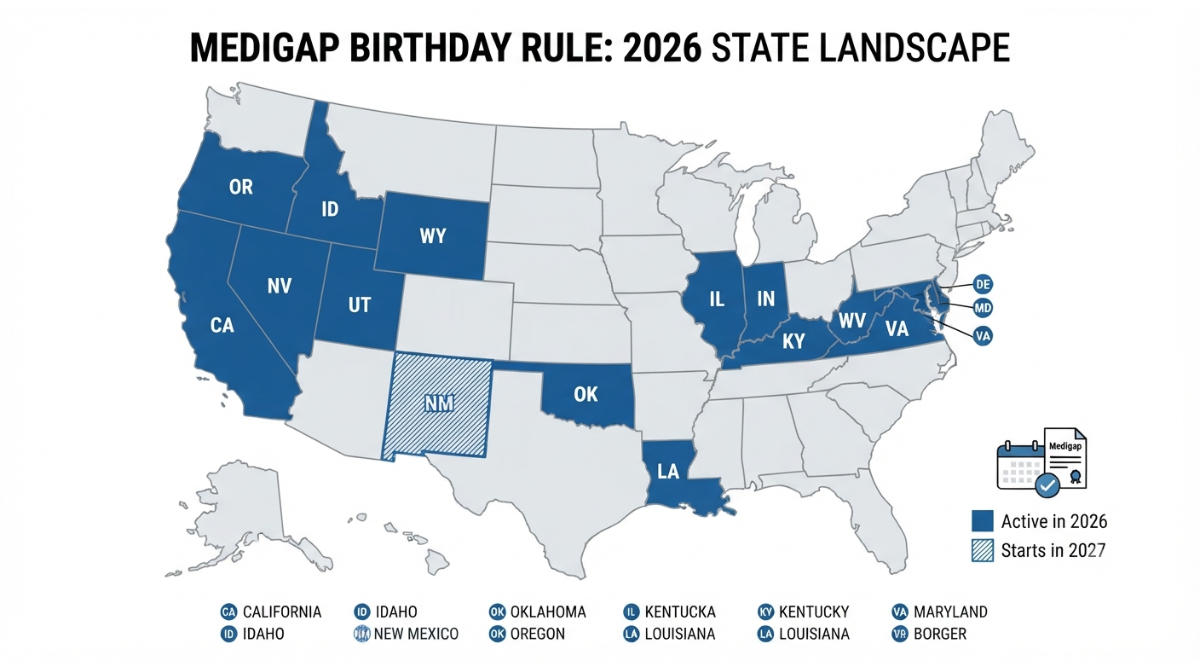
Fifteen states have a birthday rule in effect now. New Mexico enacted one in March 2026 that does not begin until January 1, 2027 — a distinction most published lists blur.
| State | Window | Plan letters | Carriers | Key detail |
|---|---|---|---|---|
| California | 60 days from birthday | Equal or lesser | Any | Statute sets 60 days as a minimum |
| Delaware | Opens 30 days before birthday | Equal or lesser | Any | Effective 2026; closing date unconfirmed |
| Idaho | 63 days from birthday | Equal or lesser | Any | In effect since March 2022 |
| Illinois | 45 days from birthday | Equal or lesser | Current or affiliate | Ages 65–75 only |
| Indiana | Around birthday — length unconfirmed | Same letter only | Any | Effective January 2026 |
| Kentucky | 60 days of birthday | Same benefits | Any | In effect since January 2024 |
| Louisiana | 63 days from birthday | Equal or lesser | Current or affiliate | Affiliates added 2023 |
| Maryland | 30 days from birthday | Equal or lesser | Any | Shortest window of the fifteen |
| Nevada | 60 days from 1st of birth month | Equal or lesser | Any | Trigger differs from California’s |
| Oklahoma | 60 days from birthday | Equal or lesser | Any | No coverage gap over 90 days |
| Oregon | 30 days before to 30 days after | Equal or lesser | Any | Self-funded group plans excluded |
| Utah | 60 days | Equal or lesser | Current insurer only | No carrier change permitted |
| Virginia | From birthday — length unconfirmed | Same letter only | Any | Available since July 2025 |
| West Virginia | 60 days from birthday | Equal or lesser | Current or affiliate | Requires 24 months on current policy |
| Wyoming | 63 days from birthday | Equal or lesser | Any | Adopted 2025 |
| New Mexico | 60 days | Equal or lesser | Any | Does not start until Jan 1, 2027 |
Verified September 15, 2026 against enacted state legislation and state insurance agency publications. Cells marked unconfirmed could not be verified to a state-level source; confirm those with your state department of insurance. State insurance law changes mid-session — your state’s insurance department is the controlling authority, not this table.
📊 Data Point: California’s window runs 60 days or more beginning on the individual’s birthday — not the first of the birth month, as several widely-read guides state. Source: California Senate Bill 407, enacted 2019, amending Health and Safety Code §1358.11(h)(1).
Three rules decide whether you can actually switch
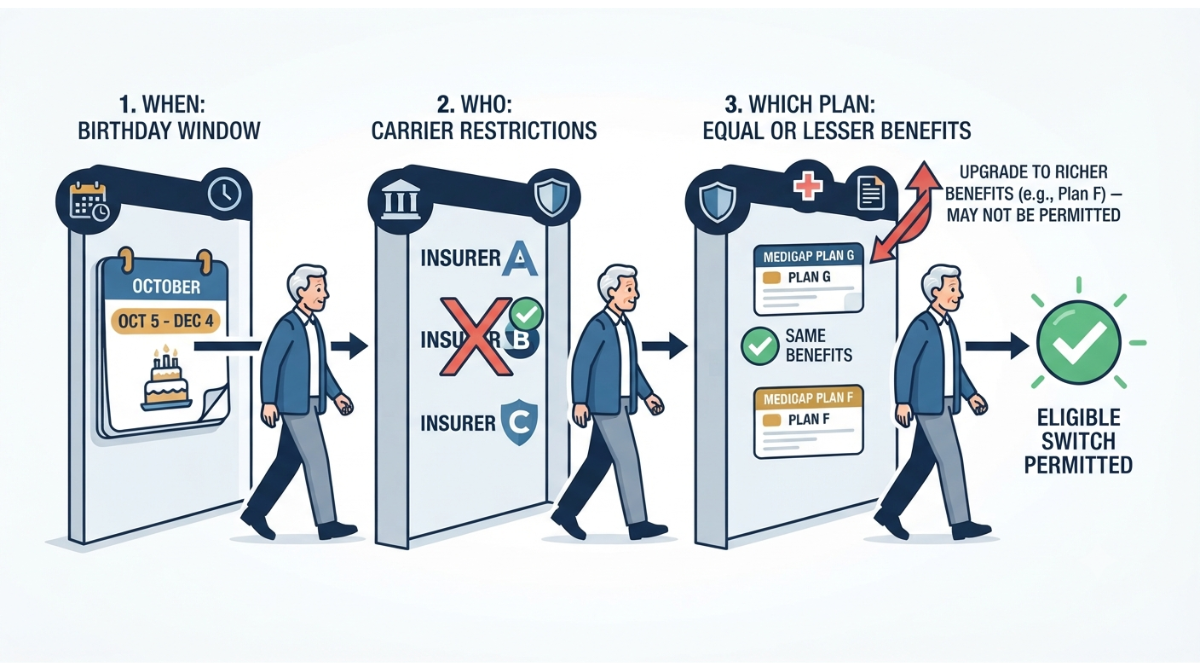
Finding your state on the list is not the same as being able to make the switch you had in mind. Three restrictions compound, and a generous window is worthless if the other two are closed.
What opens your window
Most states start the clock on your birthday. Nevada starts it on the first day of your birth month. Oregon opens 30 days before your birthday, which means Oregonians can apply while still 64 days from their next renewal.
Which companies you can move to
California, Idaho, Oregon and others let you take your business anywhere. Illinois, Louisiana and West Virginia confine you to your current insurer or an affiliate. Utah confines you to your current insurer alone — which limits the rule to changing plans, not prices.
Which plan letters are open to you
Most states permit equal or lesser benefits. A Plan G holder may move to another Plan G or down to Plan N, but never up. Indiana, Kentucky and Virginia are narrower still: same letter only.
⚠️ Costly Mistake: Applying for a richer plan during your window does not get you a guaranteed-issue approval — it gets you underwritten. A Plan N holder reaching for Plan G is making an ordinary application, and a denial for health reasons is a real outcome. Check what separates Plan G from Plan N before you assume a move is lateral.
How to use your birthday window
The process is short, and the order matters more than the speed.
- Confirm your exact dates with your state department of insurance before anything else — not from a broker’s summary.
- Identify the letter you currently hold, then list only the letters your state permits you to move to.
- Price that same letter across carriers your state allows.
- Apply inside the window and tell the insurer you are using your state’s birthday rule provision.
- Keep paying your current policy until the new one is issued in writing.
Oregon’s insurance division advises consumers not to cancel the current Medigap policy until the new one is issued, and notes that this may mean paying two premiums for a single month to keep the transfer clean. That overlap is the cost of never being uninsured.
✅ Action Step: Before you apply, call your State Health Insurance Assistance Program and ask one question: given my current plan letter and my state’s restriction, which specific plans am I eligible to switch to during my window? The counseling is free and the counselor earns nothing from your answer.
What if your state has no birthday rule
Most Americans live in the other 35 states. Several still have a guaranteed issue route.
New York and Connecticut require insurers to accept Medigap applicants year-round. Massachusetts runs an annual window each February and March. Missouri ties its window to your policy anniversary rather than your birthday — a distinction that gets it wrongly listed as a birthday-rule state.
Everywhere else, federal protection comes from the situations CMS enumerates — losing employer coverage, an insurer leaving your area, and a small number of others. The trial right for people moving back from Medicare Advantage is the one most people qualify for and least often use. You can verify your own case against the guaranteed issue situations Medicare publishes.
Mistakes that cost people their window
Trusting a state list nobody checked
Published lists disagree with each other and with the underlying law. Checking them against statute and state agency documents this month turned up errors on two of the highest-traffic states, including on pages ranking at the top of search results.
Assuming a rule applies before it does
New Mexico’s law is enacted but not operative until 2027. West Virginia requires 24 months on your current policy first. Illinois stops at age 75.
💡 Expert Note: Oregon’s own fact sheet limits the rule to policies issued after January 1, 1990 and excludes self-funded employer group plans — conditions absent from nearly every secondary summary. Read your state’s document, not a description of it.
Common questions about Medigap birthday rules
1. What is the Medigap birthday rule?
A state-created annual window letting existing Medigap holders switch plans without medical underwriting. Fifteen states have one in effect. Confirm your eligibility with a licensed agent before applying.
2. Which states have a Medigap birthday rule in 2026?
Fifteen: California, Delaware, Idaho, Illinois, Indiana, Kentucky, Louisiana, Maryland, Nevada, Oklahoma, Oregon, Utah, Virginia, West Virginia and Wyoming.
3. Can I upgrade to a better plan using the birthday rule?
No. Most states permit equal or lesser benefits only, and Indiana, Kentucky and Virginia require the same plan letter. A licensed agent can confirm your options.
4. Does the birthday rule let me change insurance companies?
In most states, yes. Illinois, Louisiana and West Virginia restrict you to your current insurer or an affiliate; Utah restricts you to your current insurer.
5. Is the Medicare Annual Enrollment Period the same as the birthday rule?
No. October 15 to December 7 governs Medicare Advantage and Part D, not Medigap. They are separate and unrelated.
6. How long is the birthday rule window?
It ranges from 30 days in Maryland to 63 days in Idaho, Louisiana and Wyoming. Check your own state’s exact figure.
7. What if my state has no birthday rule?
New York, Connecticut, Massachusetts and Missouri offer other routes, and federal guaranteed issue rights apply everywhere. Ask your SHIP counselor which applies to you.
8. Can I be denied Medigap coverage during my birthday window?
Not for a switch your state permits. An application outside those limits is underwritten normally and can be declined. Verify scope before applying.
9. When does my Medigap birthday window start?
Usually your birthday. Nevada starts on the first of your birth month, and Oregon opens 30 days before your birthday.
10. Do I have to answer health questions when switching?
Not inside a qualifying state window for a permitted switch. Outside it, insurers in most states may underwrite. Confirm with your state insurance department.
11. Should I cancel my old plan before the new one starts?
No. Keep it until the new policy is issued in writing, even if that means one month of double premiums.
Your window is a date, and dates pass. Find your state in the table, confirm it against your own insurance department, and know which letters you may move to before you price anything. A free SHIP counselor will verify all three in one phone call.
Related Articles
 Medicare
The real Medicare cost per year, added up line by line
September 2, 2026 Medicare
Are Medicare premiums tax deductible? What most retirees miss
September 12, 2026 Medicare
What health insurance really costs when retiring before 65
September 8, 2026 Medicare
How the IRMAA income lookback sets your first Medicare premium
September 4, 2026 Medicare
Do I need Part B if I’m still working? Who pays first at 65
September 7, 2026 Medicare
 Advantage vs Medigap when the costly year arrives
September 8, 2026 Medicare
RMAA brackets 2026 and the clear yearly cost of each tier
September 2, 2026 Medicare
Why COBRA Isn’t Creditable Coverage, and the Part B Risk
September 7, 2026 Medicare
 Costs: Five Separate Bills, Not One Premium
August 26, 2026
Informational disclaimer
The content on Finance Authority Hub is provided for general informational and educational purposes only and should not be considered personalized financial, investment, tax, legal, or professional advice. Financial decisions depend on your individual goals, income, risk tolerance, location, and regulatory situation. Before acting on any information, strategy, estimate, or calculator result, consult a qualified licensed professional who can evaluate your specific circumstances.