The Saver’s Match Rules Worth Knowing Before 2027
The Saver’s Match reaches zero at $35,500 for single filers in 2027 — a lower ceiling than the credit it replaces, which still covers $40,250 this year.
Independent money education for US readers. Not financial advice.

Education, not advice. Written for US readers.
The Saver’s Match reaches zero at $35,500 for single filers in 2027 — a lower ceiling than the credit it replaces, which still covers $40,250 this year.

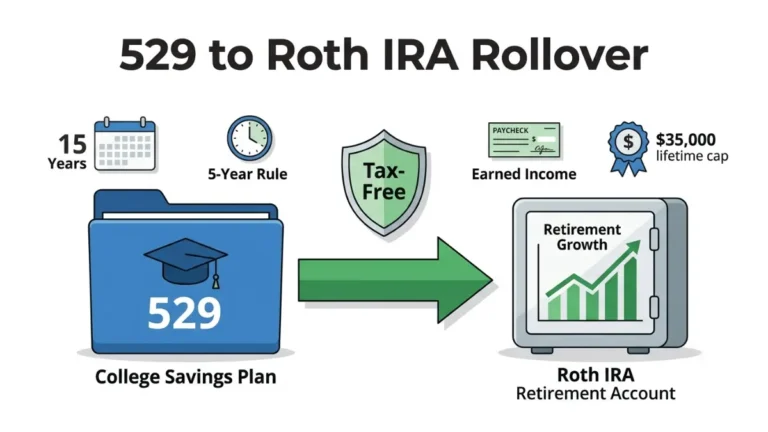
529 to Roth IRA rollovers are capped at $35,000 for life — but four separate limits decide how much moves this year, and the smallest one wins.

A 401(k) and an IRA in the same year is never a conflict. But claiming the IRA deduction can’t lower the income that decides it — only your deferral can.
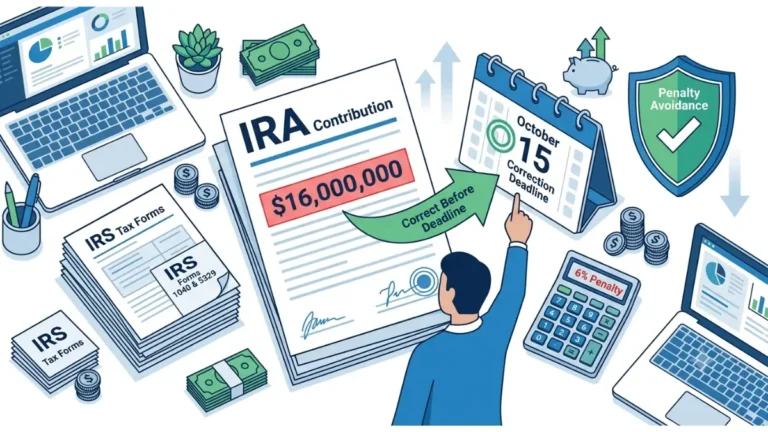
An excess IRA contribution is fixable — but a $7,500 excess can come back as $7,200, and your custodian is not making a mistake.
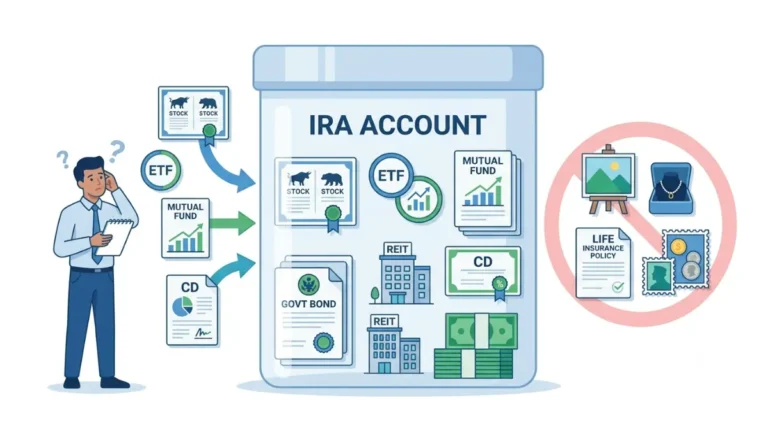
IRA investments don’t start themselves: 28% of 2022 rollovers were still in cash a year later. The money arrived. Nobody placed the trade.
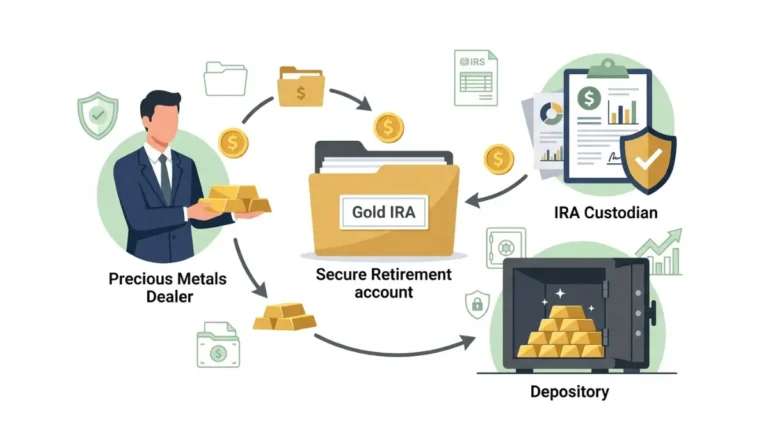
Gold IRA fees look small until you price the dealer’s spread: FINRA reports some dealers charge under 20%, some frauds over 300%. Here is the math.
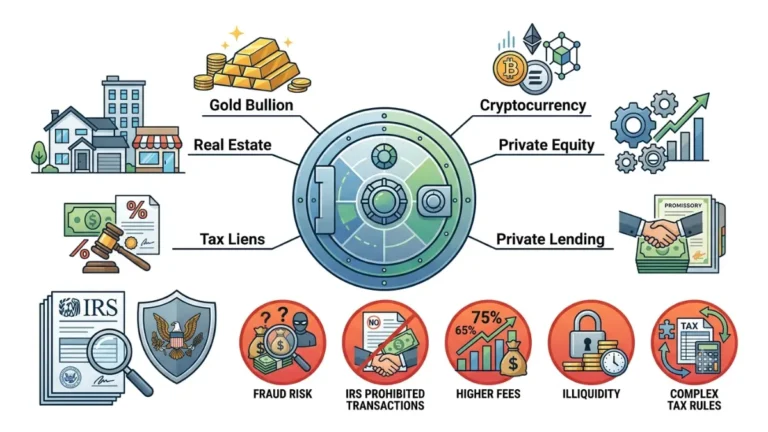
Self-directed IRA risks go past bad deals. Business or debt-financed income inside the account can be taxed at 37% above $16,000 in 2026.
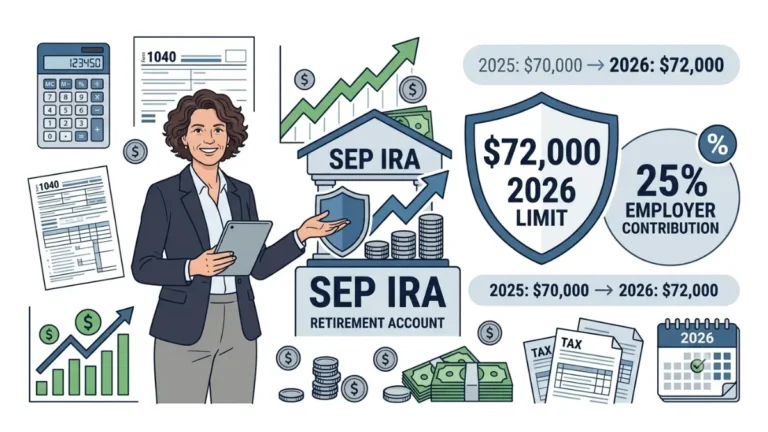
SEP IRA contribution limits look simple until you’re the employer too. The 25% rule becomes 20% once it’s applied to your own net earnings.
Spousal IRA contributions hit $7,500 for 2026 — but the income range that decides your
deduction depends on which spouse has a plan at work, not who earns.
Custodial Roth IRA contributions stop at whatever your child earned — and the way they earned it decides what that money costs in tax.