The months that decide what claiming Social Security at 62 costs
Claiming Social Security at 62 was once the majority choice — 50.8% of men in 1998. By 2024 it was 22.8%. The most common age is no longer the common one.
Independent money education for US readers. Not financial advice.

Education, not advice. Written for US readers.

Claiming Social Security at 62 was once the majority choice — 50.8% of men in 1998. By 2024 it was 22.8%. The most common age is no longer the common one.

Full retirement age decides more than your benefit: Social Security uses your retirement date, not your survivor date, to end the earnings test.
Earnings record errors in 2023 wages can be fixed through April 15, 2027. Later, employer wages still qualify; late-filed self-employment income won’t.

Social Security 35 years: among higher-earning women, 86% with no children reach 35 work years — but only 69% of those with three or more do.
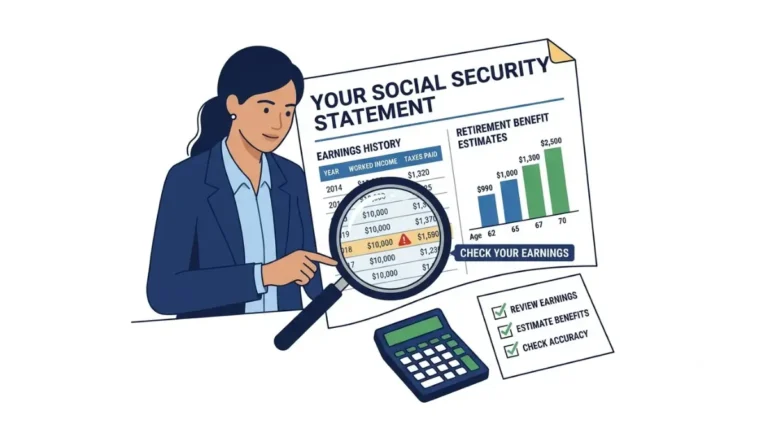
The estimate under your Social Security statement chart assumes your pay continues until you claim. SSA’s own sample assumes $54,489 a year.

Social Security work credits: SSA’s own duration table is simply your age minus 22, floored at six and capped at 40. Every published row checks out.

Average Social Security benefit hides a detail SSA publishes but nobody quotes: 62% of retired workers claimed early, and their average is $1,716.92.

Social Security bend points explain a quirk in SSA’s own 2026 examples: two workers retiring the same year, two different formulas, both correct.

How Social Security is calculated comes down to 35 indexed years and one number the government never shows you: the lowest year still counted.

Average IRA balance data comes from four sources that disagree by 3.75x for the same age band. Here’s what each one actually measures.