What a Structured Settlement Cash Advance Really Costs You
A structured settlement cash advance is legal only with a judge’s approval — and a 2026 personal loan near 12% APR often costs far less.
Independent money education for US readers. Not financial advice.

Education, not advice. Written for US readers.
A structured settlement cash advance is legal only with a judge’s approval — and a 2026 personal loan near 12% APR often costs far less.
Personal injury structured settlement talks involve five parties and one irreversible signature. Know who’s across the table before you negotiate.
Received a structured settlement offer? A CFA explains the tax-free rules and the one move to make before you sign.
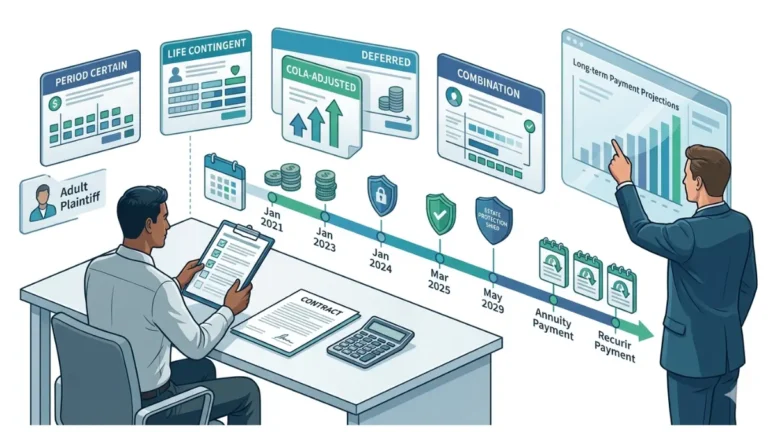
Structured settlement payment schedule types differ by more than timing — at the May 2026 IRS rate of 5.00%, each carries a very different real value.
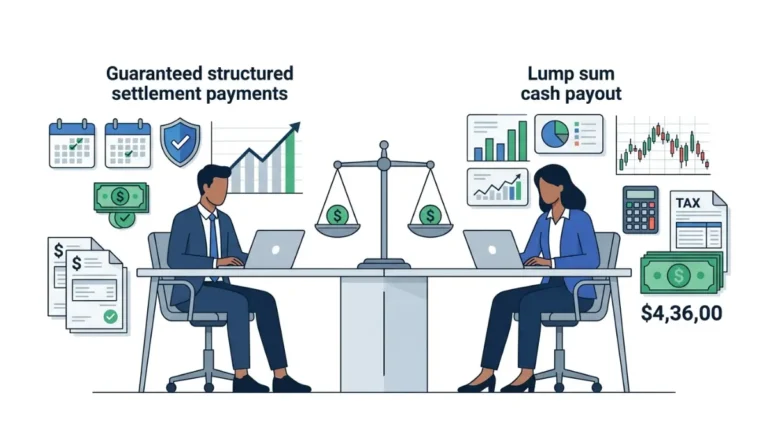
Lump sum vs structured settlement: the 2026 NPV math reveals what break-even return rate you need before a factoring offer makes financial sense.
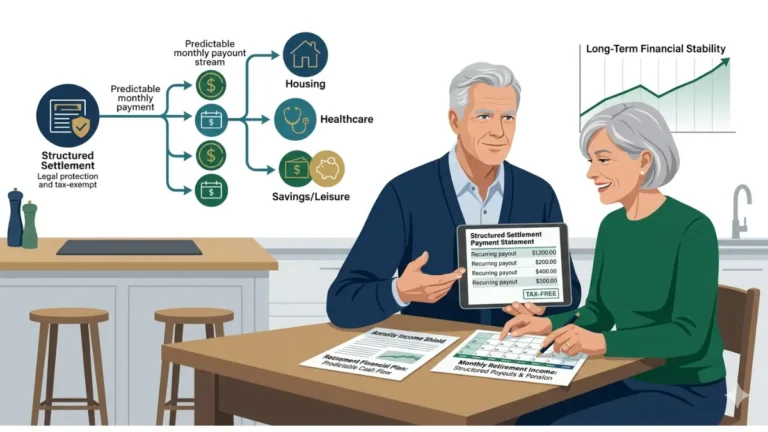
Structured settlement retirement income is federally tax-free — but one IRS carve-out and a factoring decision can erase $30,000. Know both rules first.
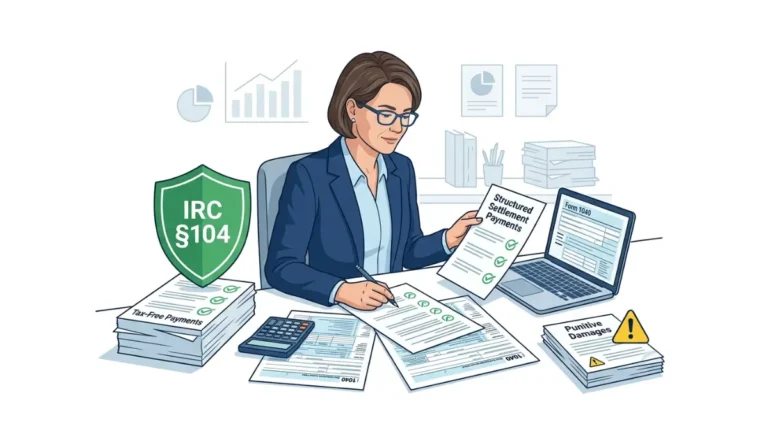
Structured settlement taxes under IRC §104 can stay excluded, but one Form 1099 mistake may trigger IRS correspondence and amended returns.
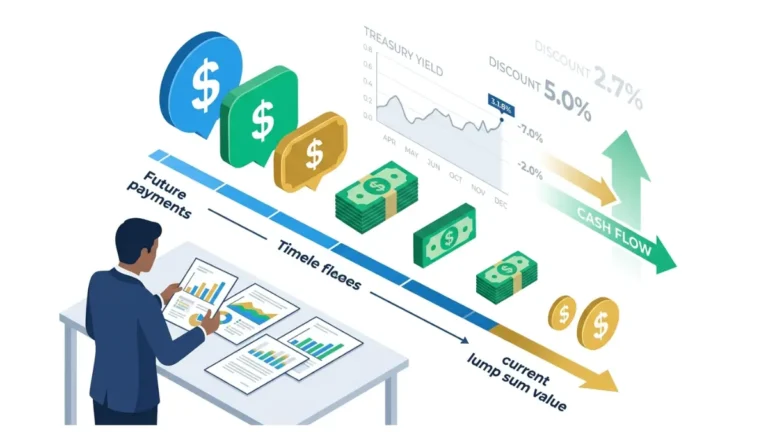
Structured settlement present value isn’t face value — a 2026 CFA calculation shows why $360,000 in payments may be worth just $124,200 to a buyer.
Sell structured settlement credit score concerns stem from confusion about FICO reporting, hard inquiries, and mortgage income verification rules.
Structured settlement loans aren’t loans — factoring companies charge 45% APR while quoting 13%. A CFA breaks down the legal block and the true cost.