
Refund Approved but No Deposit? A Clear Way to Find It
Refund approved, no deposit yet? The IRS says e-filed refunds typically take 3 weeks; see what to check once that window passes.
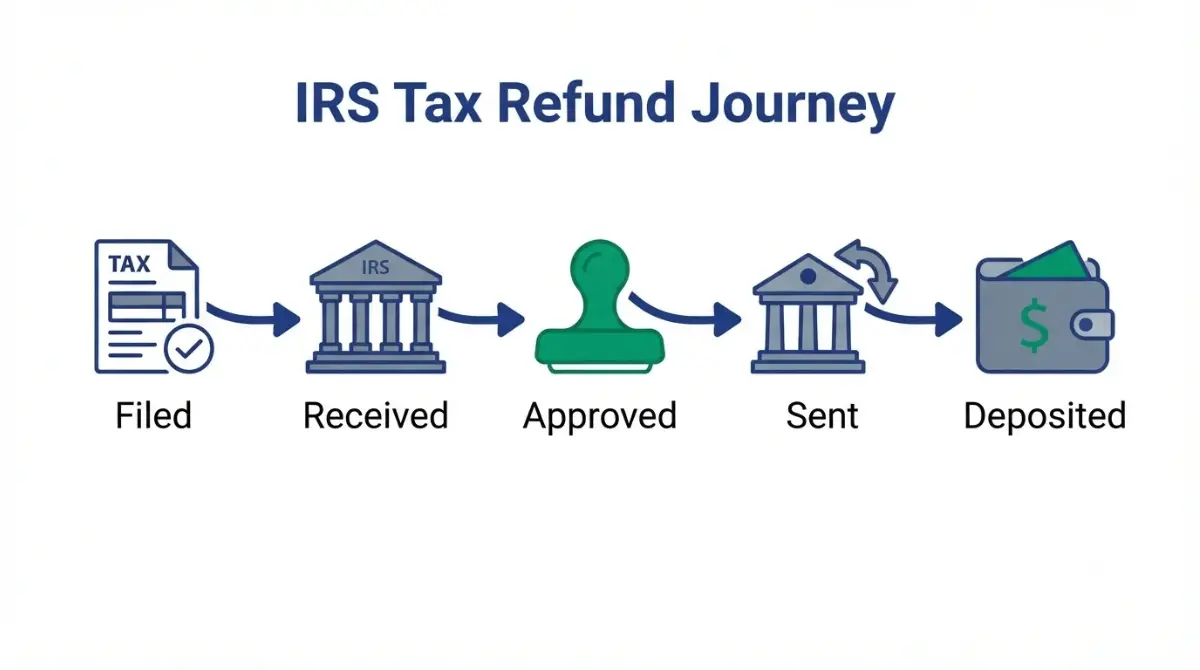
In This Article
What “refund approved” actually tells you
A refund approved status means, per IRS guidance, that the IRS is preparing to send your refund, not that it has reached your bank. Banks, mail, and offsets sit between “approved” and your balance.
Find your situation:
- Date not passed: see timing.
- Date passed: run the five checks.
- Notice received or amount off: see the notice and offset sections.
Unsure what you should receive? How a refund amount is calculated explains the formula.
ℹ️ Financial Disclaimer: This article explains federal tax refund procedures for education, not personalized tax, banking, or legal advice. A CPA or enrolled agent can review your return; the Taxpayer Advocate Service offers free help in hardship.
How long after approval should your refund arrive?
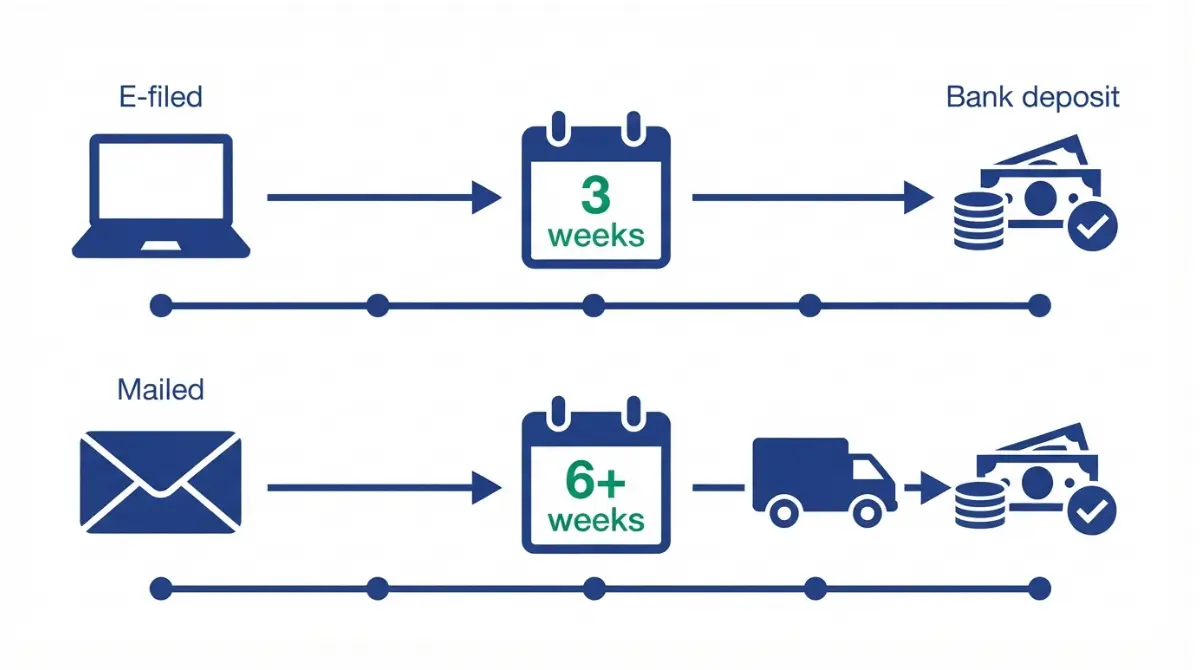
The IRS says an e-filed return typically takes 3 weeks and a mailed return 6 or more weeks, per its refunds page.
Typical timing by how you filed
Your clock starts on your e-file date or the date the IRS received your paper return. The refund schedule from filing day to deposit day shows how to count it.
When a missing deposit becomes a problem
| Situation | Window | Key Detail |
|---|---|---|
| E-filed | 3 weeks | IRS refunds page, June 2026 |
| Mailed | 6+ weeks | IRS refunds page, June 2026 |
| Missing deposit | 5 calendar days after contacting your bank | File Form 3911; an older IRS page says two weeks |
Refund approved, no deposit: five checks to run first
Check these five things in order:

- Check the tracker status and date.
- Check every account you listed, including prepaid cards, apps, and refund transfer accounts.
- Check mail and your IRS online account for notices.
- Compare the amount received with your return.
- Compare the routing and account numbers with your bank.
Check the tracker and your bank
Refund status appears 24 hours after you e-file. The IRS accepts bank, app, and prepaid card accounts, so check each.
Check mail and your IRS online account
A CP53C, CP53E, or offset notice can explain the gap. Open Notifications online.
Compare the amount and the account number
Estimate your expected refund with an income tax calculator, then match every digit.
What a CP53C or CP53E notice means for your refund
A CP53C notice means the IRS tried to direct deposit your refund, but your financial institution couldn’t process it.
| Notice | What happened | Key Detail |
|---|---|---|
| CP53C | Deposit couldn’t be processed | Wait up to 10 weeks |
| CP53E | Bank information invalid, missing, or rejected | Update within 30 days |
Source: IRS pages on the CP53C (January 2026) and CP53E (May 2026) notices.
CP53C: the bank returned the deposit
- The IRS researches your account first.
- Expect up to 10 weeks for a refund check or follow-up letter.
- Calling won’t speed it up; call the number on your notice if 10 weeks pass.
🔍 How It Works: A rejected deposit returns to the IRS, which reviews your account and return before releasing money.
CP53E: the IRS has no usable account
Under Notifications in your online account, select Add bank account within 30 days. Otherwise the IRS issues a paper check after 6 weeks.
✅ Action Step: If 10 weeks pass or hardship follows, ask the Taxpayer Advocate Service: “Can you open a case for my missing CP53C refund?”
Does the IRS still mail refund checks?
The IRS says it generally stopped issuing paper refund checks after Sept. 30, 2025, with limited exceptions. Its notices still mention checks, so update your bank details rather than wait for one.
Refund reduced or taken: adjustment vs. offset
A refund is usually smaller for one of two reasons:
- The IRS adjusted it.
- The Bureau of the Fiscal Service offset it.
Adjusted by the IRS
The IRS lists math errors, ineligible credits, prior taxes owed, and underpaid estimated taxes. See the IRS guidance on reduced refunds, and compare your amount with 2026 refund amounts.
Offset by the Bureau of the Fiscal Service
Offsets cover debts such as child support, federal debts, state income taxes, and unemployment compensation. The Bureau mails a notice showing the original refund, the offset, and the agency; call 800-304-3107 with questions. Joint filers reduced for a spouse’s debt may request injured spouse relief.
Who holds your money, and who to call
| Symptom | Who holds it | What to do |
|---|---|---|
| Another person’s account accepted the funds | That account’s bank | Contact the bank; file Form 3911 after 5 calendar days |
| Refund transfer | A temporary account at the preparer’s bank | Ask the preparer; fees may be deducted |
| Three-refund limit exceeded | The IRS | Watch for a notice and paper refund |
| Account not in your name | The account owner | Contact that bank; file Form 3911 |
Sources: IRS FAQ on wrong account numbers (September 2026); IRS direct deposit page (May 2026); CFPB refund transfer guidance (2018).
Starting a refund trace with Form 3911
Banks have up to 90 days to answer the IRS, and a trace may take 120 days. The IRS says to use accounts in your name, your spouse’s, or joint, with no more than three refunds per account.
Four mistakes that slow a missing refund
- Calling during the CP53C wait. The IRS says calling won’t speed your refund.
- Missing the CP53E 30-day deadline. Add your account online first.
- Updating bank details by phone. IRS phone staff can’t make that change.
- Checking status off irs.gov. Use the IRS tracker.
Run the checks in order, and if a window passes, start the trace or call the number on your notice.
Refund approved but no deposit: FAQ
1. Why does my refund say approved but I have no deposit?
Approved means the IRS is preparing to send the refund; the deposit or mailed payment follows afterward.
2. How long should I wait before contacting my bank?
Wait out the IRS’s typical window: 3 weeks if e-filed, 6 or more if mailed. If a deposit is missing, contact your bank first.
3. What is Form 3911?
Form 3911 asks the IRS to trace a missing refund; file it after contacting your bank and 5 calendar days pass with no deposit.
4. What does a CP53C notice mean?
A CP53C notice means the IRS tried to direct deposit your refund, but your financial institution couldn’t process it.
5. Why can a CP53C refund take up to 10 weeks?
The IRS researches your account first and says up to 10 weeks may pass before a refund check or follow-up letter.
6. What is a CP53E notice?
A CP53E notice says your bank information is invalid, missing, or rejected, and gives you 30 days to update it.
7. Can I update my bank account by phone?
No. For a CP53E notice, add the account under Notifications in your IRS online account; phone staff can’t update it.
8. Why was my refund smaller or taken?
The IRS may adjust it for errors, credits, or taxes owed, or the Bureau of the Fiscal Service may offset it for debts.
9. Can the IRS send my refund to a relative’s account?
The IRS says to use only accounts in your name, your spouse’s name, or a joint account, with no more than three refunds per account.
10. What if my refund went into someone else’s account?
Contact the receiving bank, then file Form 3911 once 5 calendar days pass; banks have up to 90 days to answer the IRS.
11. Does the IRS still mail refund checks?
The IRS says it generally stopped issuing paper refund checks after Sept. 30, 2025, with limited exceptions, so keep direct deposit details current.
For decisions about your own return, ask a CPA or enrolled agent whether your bank details or an offset explain the delay; the Taxpayer Advocate Service offers free help if the delay causes hardship.
Related Articles
 Tax Refund
The Right Way to Check Your Tax Refund Status With the IRS
October 6, 2026 Tax Refund
 Delayed and Bills Running Late? Find the Cause First
October 7, 2026 Tax Refund
Where to Put Tax Refund Money for a Smart 3-Month Hold
October 15, 2026 Tax Refund
A Smart Way to Plan Around Your PATH Act Refund Date
October 8, 2026 Tax Refund
A Clear Tax Refund Formula You Can Run on Your Own Numbers
October 6, 2026 Tax Refund
Is Your Tax Refund Lower Than Last Year? Find the Real Reason
October 10, 2026 Tax Refund
How Injured Spouse Relief Returns Your Share of a Joint Refund
October 21, 2026 Tax Refund
Self-Employed Tax Refund or Bill? A Clear 2026 Walkthrough
October 14, 2026 Tax Refund
Do You Need to File to Get a Tax Refund If You Owe Nothing?
October 12, 2026
Informational disclaimer
The content on Finance Authority Hub is provided for general informational and educational purposes only and should not be considered personalized financial, investment, tax, legal, or professional advice. Financial decisions depend on your individual goals, income, risk tolerance, location, and regulatory situation. Before acting on any information, strategy, estimate, or calculator result, consult a qualified licensed professional who can evaluate your specific circumstances.