Annuity vs. Life Insurance — Which One Fits You?
Annuity vs. life insurance isn’t either/or — U.S. annuity sales hit a record $464.1B in 2025, while ~100 million adults remain underinsured.
Independent money education for US readers. Not financial advice.

Education, not advice. Written for US readers.
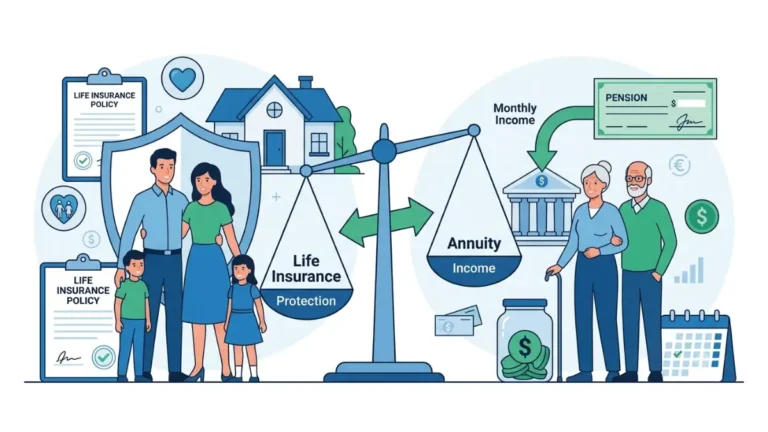
Annuity vs. life insurance isn’t either/or — U.S. annuity sales hit a record $464.1B in 2025, while ~100 million adults remain underinsured.
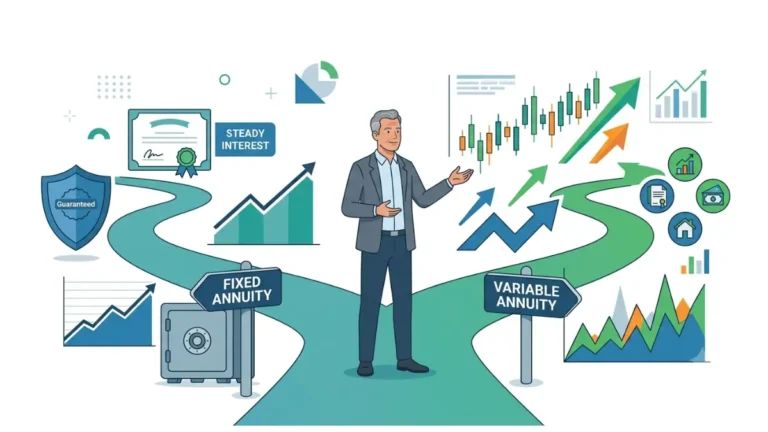
Fixed vs. variable annuity: one locks in your rate with almost no fees, the other adds 2–4% yearly costs and puts market risk on you.
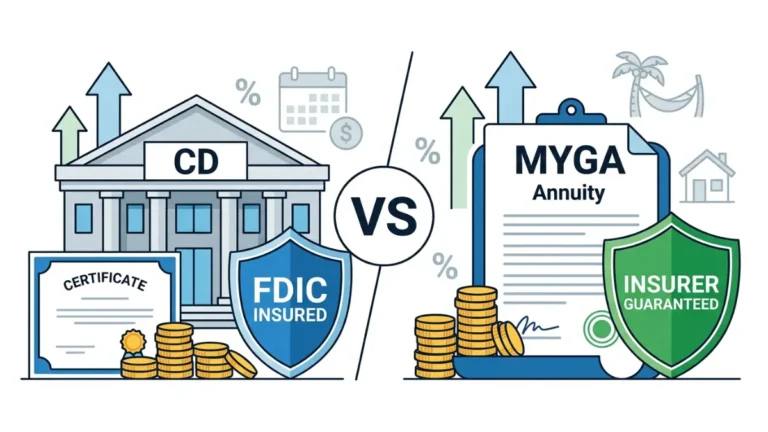
Annuity vs. CD: a MYGA can pay 1–2 points more than a CD, but it locks up your money and isn’t FDIC-insured. Here’s how to weigh the higher yield.
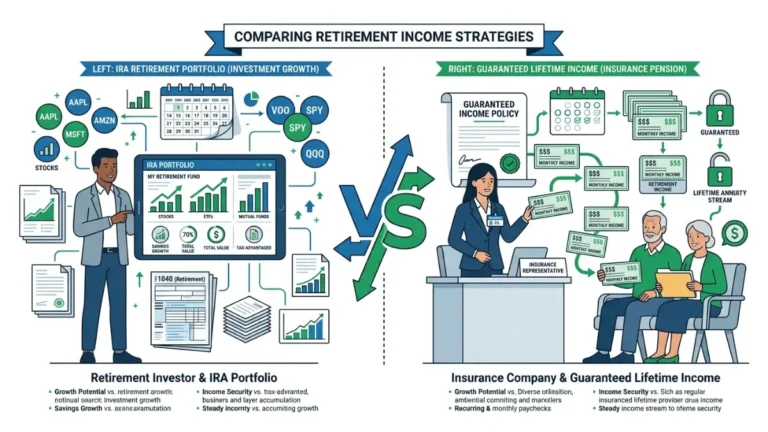
The annuity vs. IRA gap starts with one number — $7,500, the 2026 IRA cap. Annuities carry no IRS limit, and the two are taxed on very different rules.
An annuity vs. 401(k) isn’t a fair fight — one builds savings, the other pays income for life. See how taxes, the 10% penalty, and fees really compare.
Average annuity returns aren’t one number. An income annuity’s ‘payout’ includes your own principal back, so the real return is far lower than it looks.
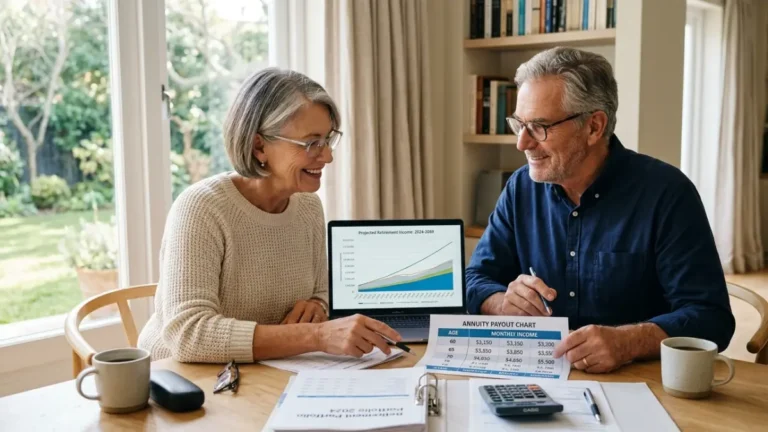
Annuity payout rates by age rise sharply: the same $100,000 buys a 65-year-old about $633/month and a 75-year-old $825 — here’s why, and the tax catch.
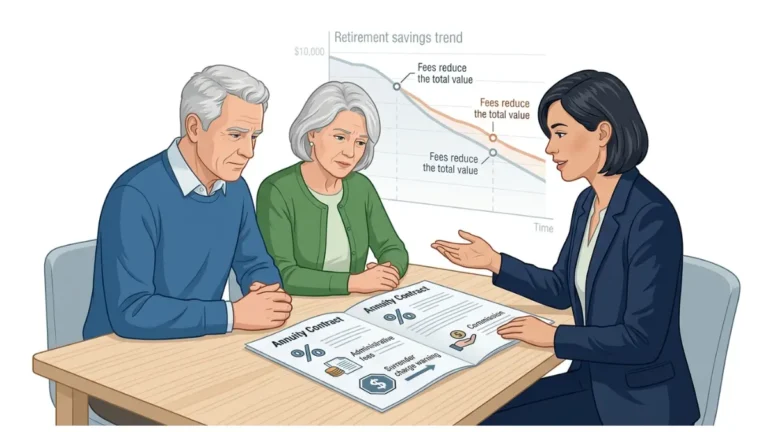
Annuity fees hide in plain sight. In a 2026 FINRA case, switching annuities cost 114 savers an average of $8,718.86 each. See every annuity fee.
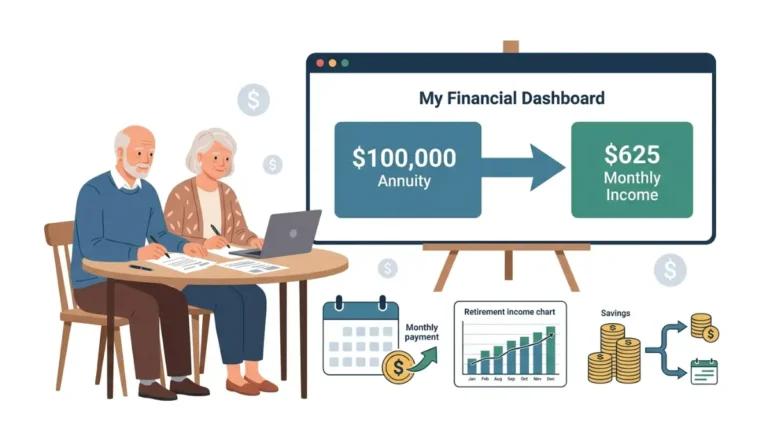
A $100,000 annuity can pay roughly $530 to $1,080 a month—but the figure swings on your age, your payout choice, and what the IRS treats as taxable.
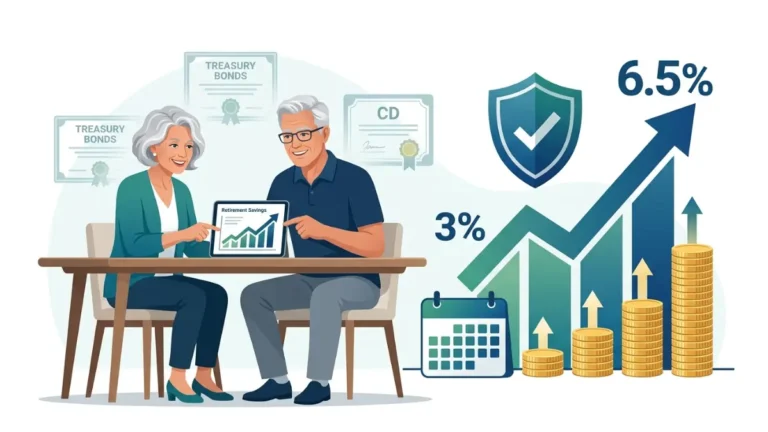
Annuity rates are near 15-year highs and top MYGAs now out-yield CDs — but the highest advertised rate isn’t always the best deal.