
What to Do With Tax Refund Money in a Clear, Simple Order
Your tax refund can keep a $400 surprise off a card. 63% of adults say they would cover one with cash or its equivalent. Check where you stand.
In This Article
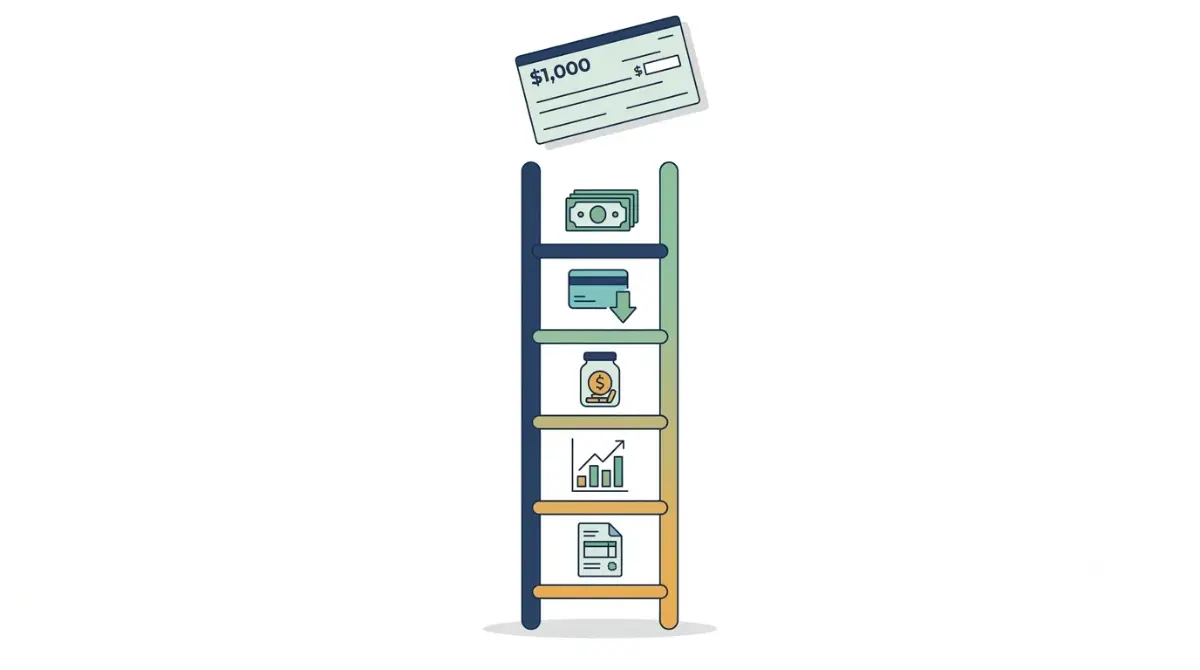
What to do with a $1,000 tax refund, in order
The ladder in one list
Use a $1,000 tax refund in this order:
- Build a $400 cash cushion.
- Pay down credit card balances.
- Keep what is left in a savings account.
- Add to an IRA if you qualify.
- Fix your withholding.
This is a common order, not a rule. The IRS reported an average refund of $3,276 through May 8, 2026, so $1,000 is a smaller refund and the order matters more.
If your refund has not arrived yet
If a surprise bill would land on your card, start at step 1. If you already carry a balance, start at step 2.
Still waiting on your deposit? See how the refund schedule works from filing to deposit.
ℹ️ Financial Disclaimer: This article is educational and is not personalized investment, tax, lending, debt-relief or insurance advice. Rates and limits change, and each figure shows the month it was read. Before acting, ask a CPA or Enrolled Agent about tax and IRA questions, a nonprofit credit counselor about debt, and a fiduciary advisor about investing.
Start with a $400 cushion before anything else
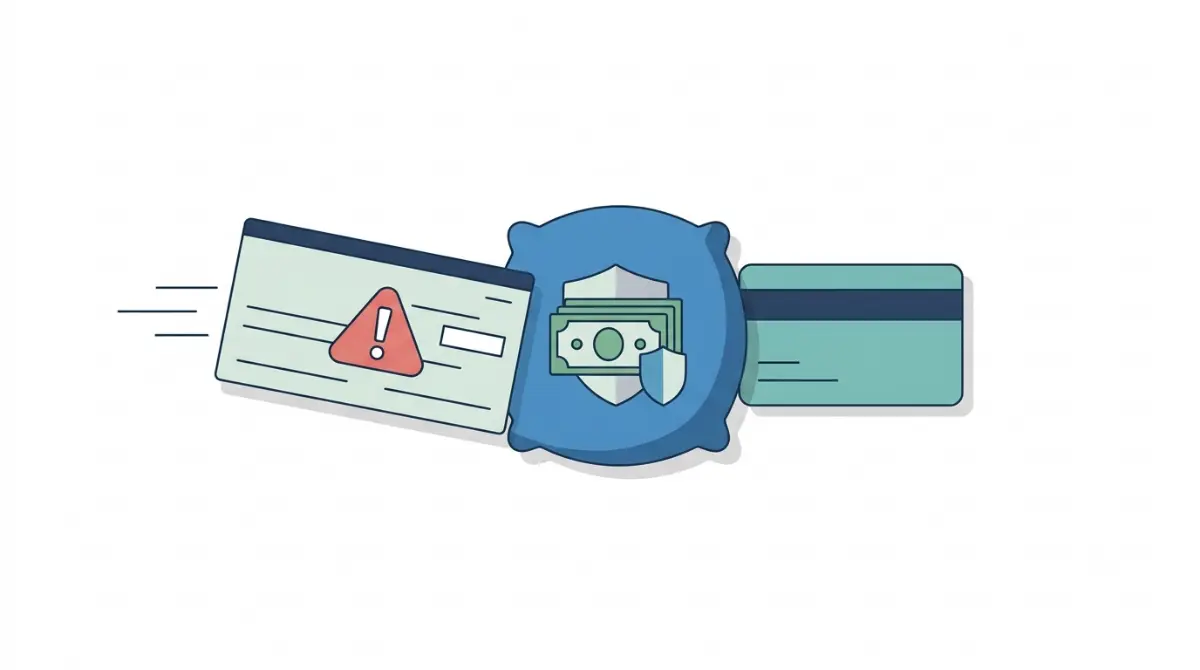
The $400 test
A small emergency fund keeps the next surprise off your card. Without one, an unexpected bill can land on a card, which is the cost step 2 measures.
📊 Data Point: 63% of adults said they would cover a hypothetical $400 emergency expense using cash or its equivalent. Source: Federal Reserve, Economic Well-Being of U.S. Households in 2025 (May 2026).
That is a survey test amount, not a savings target. If you could not cover $400 today, put part of your refund here first.
If you already pass it
Skip to step 2. Your cushion already does its job; keep it somewhere you can reach quickly.
Should a $1,000 refund pay down credit card debt?
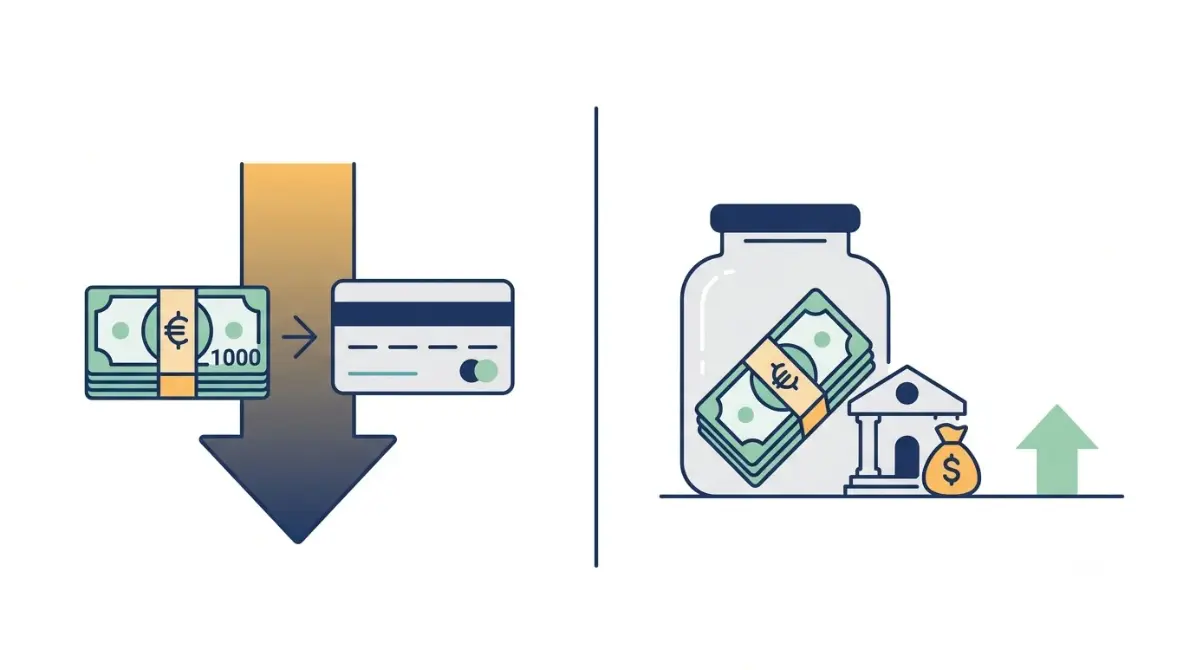
What $1,000 costs on a card
Card interest is a yearly cost you can measure against what savings pay.
📊 Data Point: 22.36% is the average credit card rate for accounts assessed interest in August 2026 (preliminary). Source: Federal Reserve G.19 release, October 7, 2026.
Your own APR is on your statement and may differ.
How it compares with savings
| Where $1,000 sits | Yearly amount | Key detail |
|---|---|---|
| Card balance at 22.36% | $223.60 cost | Cost removed |
| Savings at 0.37% | $3.70 earned | Earnings |
Sources: Federal Reserve G.19; FDIC national rate; editor’s arithmetic.
🔍 How It Works: Yearly interest is about balance × APR, ignoring compounding and payments.
If your balance is bigger than your refund
✅ Action Step: Ask a nonprofit credit counselor whether a repayment plan can lower the rate on any balance above your refund.
What does $1,000 earn in a savings account?
What the national average pays
Where your cash sits decides how much it earns. The FDIC’s national average savings rate was 0.37% in September 2026, so $1,000 earns about $3.70 in a year, roughly 31 cents a month.
What a higher-rate account could add
Rates differ by bank. At an example 4.00% APY, $1,000 would earn $40 a year; that is an illustration, not a quote. For context, the Federal Reserve set its target range at 3.75% to 4.00% on September 16, 2026.
The gap between $3.70 and $40 is why accounts are worth comparing. Check any bank’s current APY before moving money, or try your own balance in the savings calculator.
Can you put a tax refund into an IRA?
The 2026 limit
Yes, the IRS says a split refund can include your Individual Retirement Account. The 2026 IRA limit is $7,500, so $1,000 uses 13.3% of it. See what regular deposits could add in the retirement calculator.
When income changes the answer
A Roth IRA contribution phases out between $153,000 and $168,000 of income for single filers, and $242,000 to $252,000 for married couples filing jointly. Traditional IRA deductions also depend on income and workplace plan coverage. A paycheck 401(k) with an employer match is a separate route.
✅ Action Step: Ask a CPA or Enrolled Agent: “Is my IRA contribution deductible, and am I under the Roth income range for my filing status?”
How to split your refund and stop overpaying next year
Splitting the deposit
Each part of a refund can land where you want it. The IRS lets you split a direct-deposit refund across up to three accounts in tax software, or on Form 8888 with a paper return.
Checking your withholding
A refund means your payments and credits exceeded your tax; see how your refund is calculated. Run the IRS Tax Withholding Estimator with a recent pay stub, then give your employer an updated Form W-4. Lower withholding raises your paycheck, shrinks the refund and can leave tax due, which the paycheck calculator helps you preview.
✅ Action Step: Ask a CPA or Enrolled Agent: “What W-4 change keeps me from owing at filing?”
Mistakes that waste a $1,000 refund
Funding the wrong rung first
Putting the whole refund in an IRA while you carry a card balance and have no cushion reverses the order above. Fix the order first, then add to the IRA with what is left.
Spending it all with no plan
A planned treat is part of a plan. An unplanned one is how $1,000 disappears. Decide the share before the deposit lands, and write it down.
Counting on the same refund next year
⚠️ Costly Mistake: Budgeting bills around a refund. Spread over 12 months, $1,000 is about $83.33 a month, and a W-4 change can shrink next year’s refund, so plan from your paycheck.
What to do with a tax refund: common questions
1. What is the best thing to do with a $1,000 tax refund?
Spend a $1,000 tax refund in this order: a $400 cash cushion, card balances, savings, an IRA if you qualify, then withholding. A CPA or nonprofit credit counselor can check the order against your situation.
2. Should I pay off debt or save my tax refund?
Card interest at 22.36% costs about $223.60 a year on $1,000, while savings at 0.37% earn about $3.70. For larger balances, ask a nonprofit credit counselor about a repayment plan.
3. How much of my tax refund should go to an emergency fund?
Start with a $400 cushion; 63% of adults say they could cover that in cash. It is a survey test amount, not a savings target.
4. Is it smart to put a tax refund toward a credit card balance?
Often, yes: $1,000 on a card at 22.36% costs about $223.60 a year in interest, and paying it down removes that cost. A nonprofit credit counselor can review larger balances.
5. Can I split my tax refund between accounts?
Yes. The IRS lets you split a direct-deposit refund across up to three accounts using tax software, or Form 8888 on a paper return.
6. Can I put my tax refund in an IRA?
Yes. The 2026 IRA limit is $7,500, so $1,000 uses 13.3% of it; Roth eligibility depends on income. Ask a CPA or Enrolled Agent about your case.
7. How much interest does $1,000 earn in savings?
At the 0.37% national average savings rate for September 2026, $1,000 earns about $3.70 in a year.
8. What is a good use of a small tax refund?
A $1,000 tax refund is below the $3,276 average, so follow the same order: cushion, card balance, savings, IRA, withholding. Ask a CPA or nonprofit credit counselor about your case.
9. Should I change my W-4 if I get a big refund?
Check withholding with the IRS Tax Withholding Estimator first; lower withholding means a smaller refund and possible tax due. Ask a CPA or Enrolled Agent about your case.
10. Is it okay to spend part of my tax refund?
Yes, if it is planned. Cover the cushion and card balance first, then spend a share you chose in advance.
11. What is the average tax refund in 2026?
The IRS reported an average refund of $3,276 for 2026 returns processed through May 8, 2026.
Your next step for this refund
Cushion, card, savings, IRA, withholding: that is the order. Before your next paycheck cycle, take your latest pay stub and run the IRS Tax Withholding Estimator, so next year’s refund is the size you choose. Then send this refund where the ladder says, and repeat the same order each year so the decision stays simple.
Related Articles
 Tax Refund
A Clear Tax Refund Schedule, From Filing Day to Deposit Day
October 7, 2026 Tax Refund
How to Make a Smart Tax Refund IRA Contribution for 2026
October 15, 2026 Tax Refund
A Clear Look at Tax Refund vs Owing, Run as Math
October 12, 2026 Tax Refund
A Clear Walk Through the Tax Withholding Estimator Screens
October 13, 2026 Tax Refund
Self-Employed Tax Refund or Bill? A Clear 2026 Walkthrough
October 14, 2026 Tax Refund
Where to Put Tax Refund Money for a Smart 3-Month Hold
October 15, 2026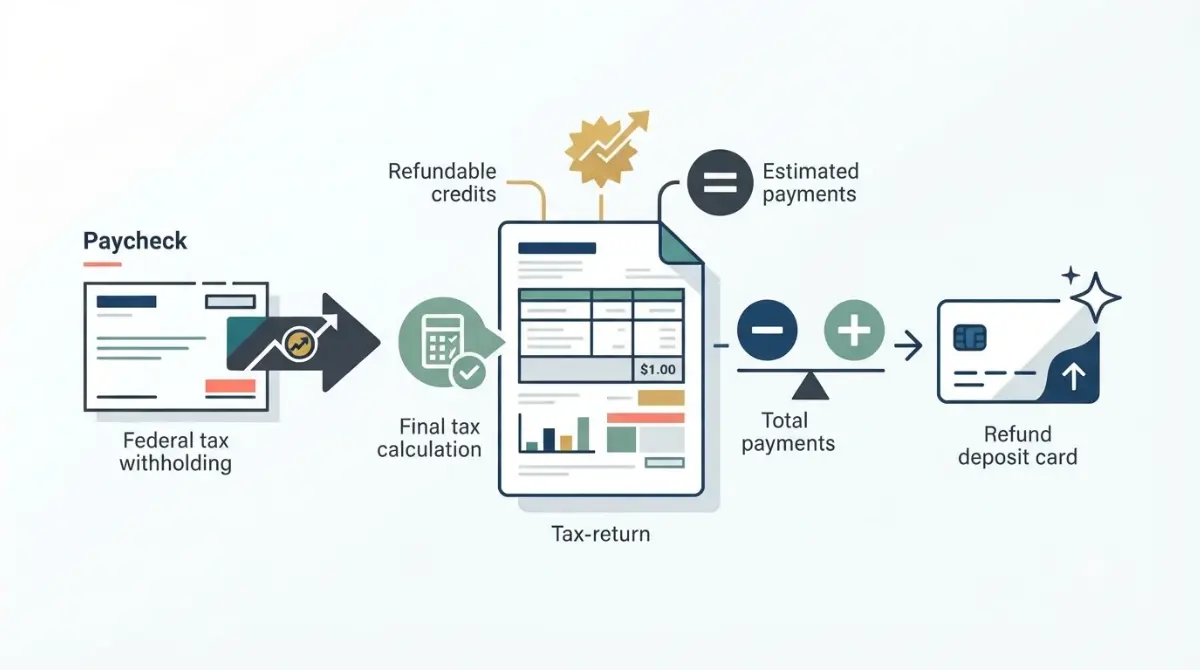 Tax Refund
A Clear Tax Refund Formula You Can Run on Your Own Numbers
October 6, 2026 Tax Refund
Refund Approved but No Deposit? A Clear Way to Find It
October 7, 2026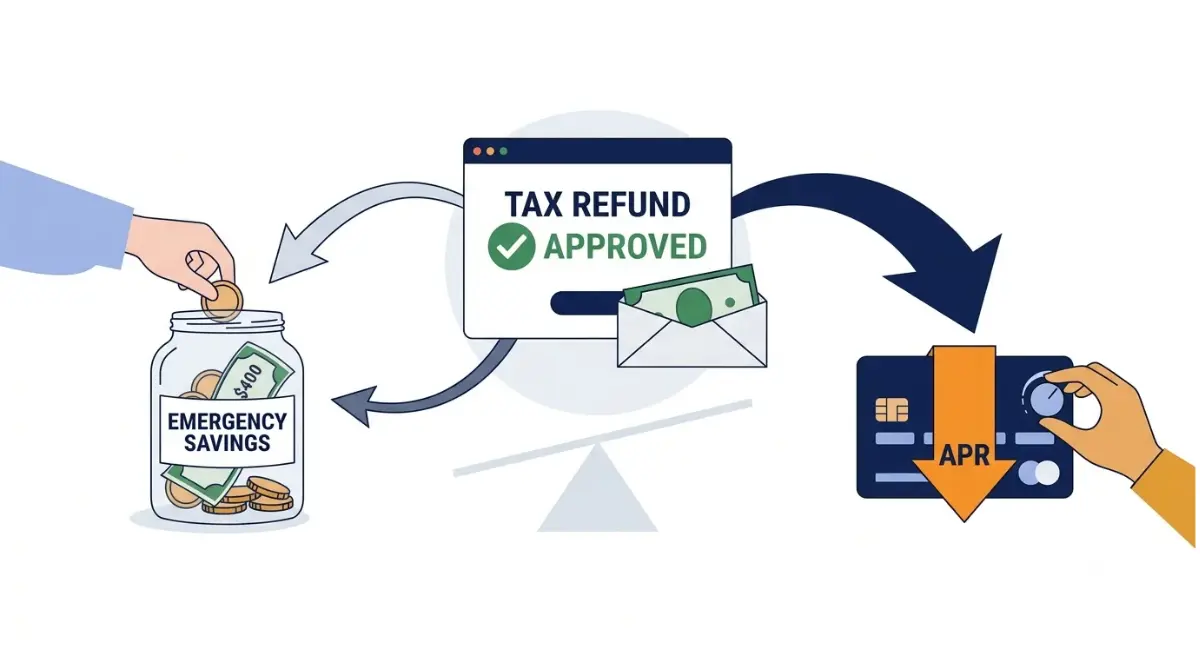 Tax Refund
Should Your Tax Refund Pay Debt or Save? Find the Right Split
October 14, 2026
Informational disclaimer
The content on Finance Authority Hub is provided for general informational and educational purposes only and should not be considered personalized financial, investment, tax, legal, or professional advice. Financial decisions depend on your individual goals, income, risk tolerance, location, and regulatory situation. Before acting on any information, strategy, estimate, or calculator result, consult a qualified licensed professional who can evaluate your specific circumstances.