The key date in how to apply for Social Security

How to apply for Social Security online carries one gap: SSA’s own manual says the form cannot capture your intent to file for a spouse or child.
Independent money education for US readers. Not financial advice.
Education, not advice. Written for US readers.
 BySameer Patel
Last Updated:
How to apply for Social Security online carries one gap: SSA’s own manual says the form cannot capture your intent to file for a spouse or child.
 BySameer Patel
Last Updated:
The Social Security earnings limit is usually temporary — but SSA’s own 2026 publication names one group who never gets the money back.
 BySameer Patel
Last Updated:
The Social Security break-even age research everyone quotes — 90% should wait to 70 — reports just 12.5% once you assume a maximum lifespan of 80.
 BySameer Patel
Last Updated:
Claiming Social Security at 62 was once the majority choice — 50.8% of men in 1998. By 2024 it was 22.8%. The most common age is no longer the common one.
 BySameer Patel
Last Updated:
Full retirement age decides more than your benefit: Social Security uses your retirement date, not your survivor date, to end the earnings test.
 BySameer Patel
Last Updated:
Social Security 35 years: among higher-earning women, 86% with no children reach 35 work years — but only 69% of those with three or more do.
 BySameer Patel
Last Updated:
Average Social Security benefit hides a detail SSA publishes but nobody quotes: 62% of retired workers claimed early, and their average is $1,716.92.
 BySameer Patel
Last Updated:
Social Security bend points explain a quirk in SSA’s own 2026 examples: two workers retiring the same year, two different formulas, both correct.
 BySameer Patel
Last Updated:
The Saver’s Match reaches zero at $35,500 for single filers in 2027 — a lower ceiling than the credit it replaces, which still covers $40,250 this year.
 BySameer Patel
Last Updated:
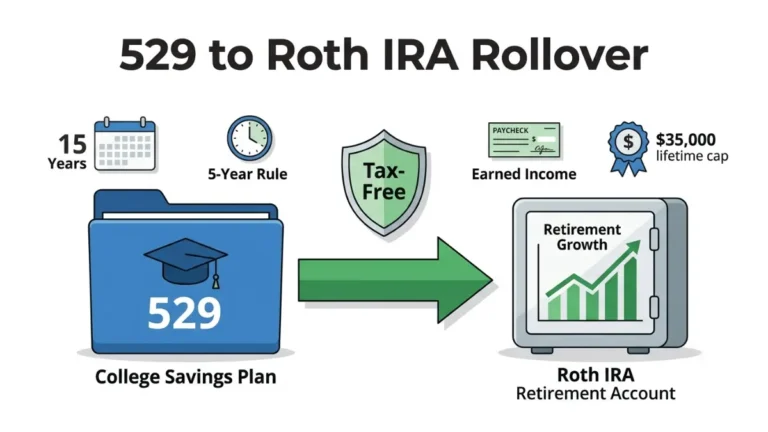
529 to Roth IRA rollovers are capped at $35,000 for life — but four separate limits decide how much moves this year, and the smallest one wins.